
BOJ hikes short‑term rate to 1.25%, highest since 1995, citing energy‑driven inflation
Tokyo – The Bank of Japan (BOJ) announced on Tuesday that it will raise its short‑term policy rate by a quarter of a percentage point to 1.25 percent, the
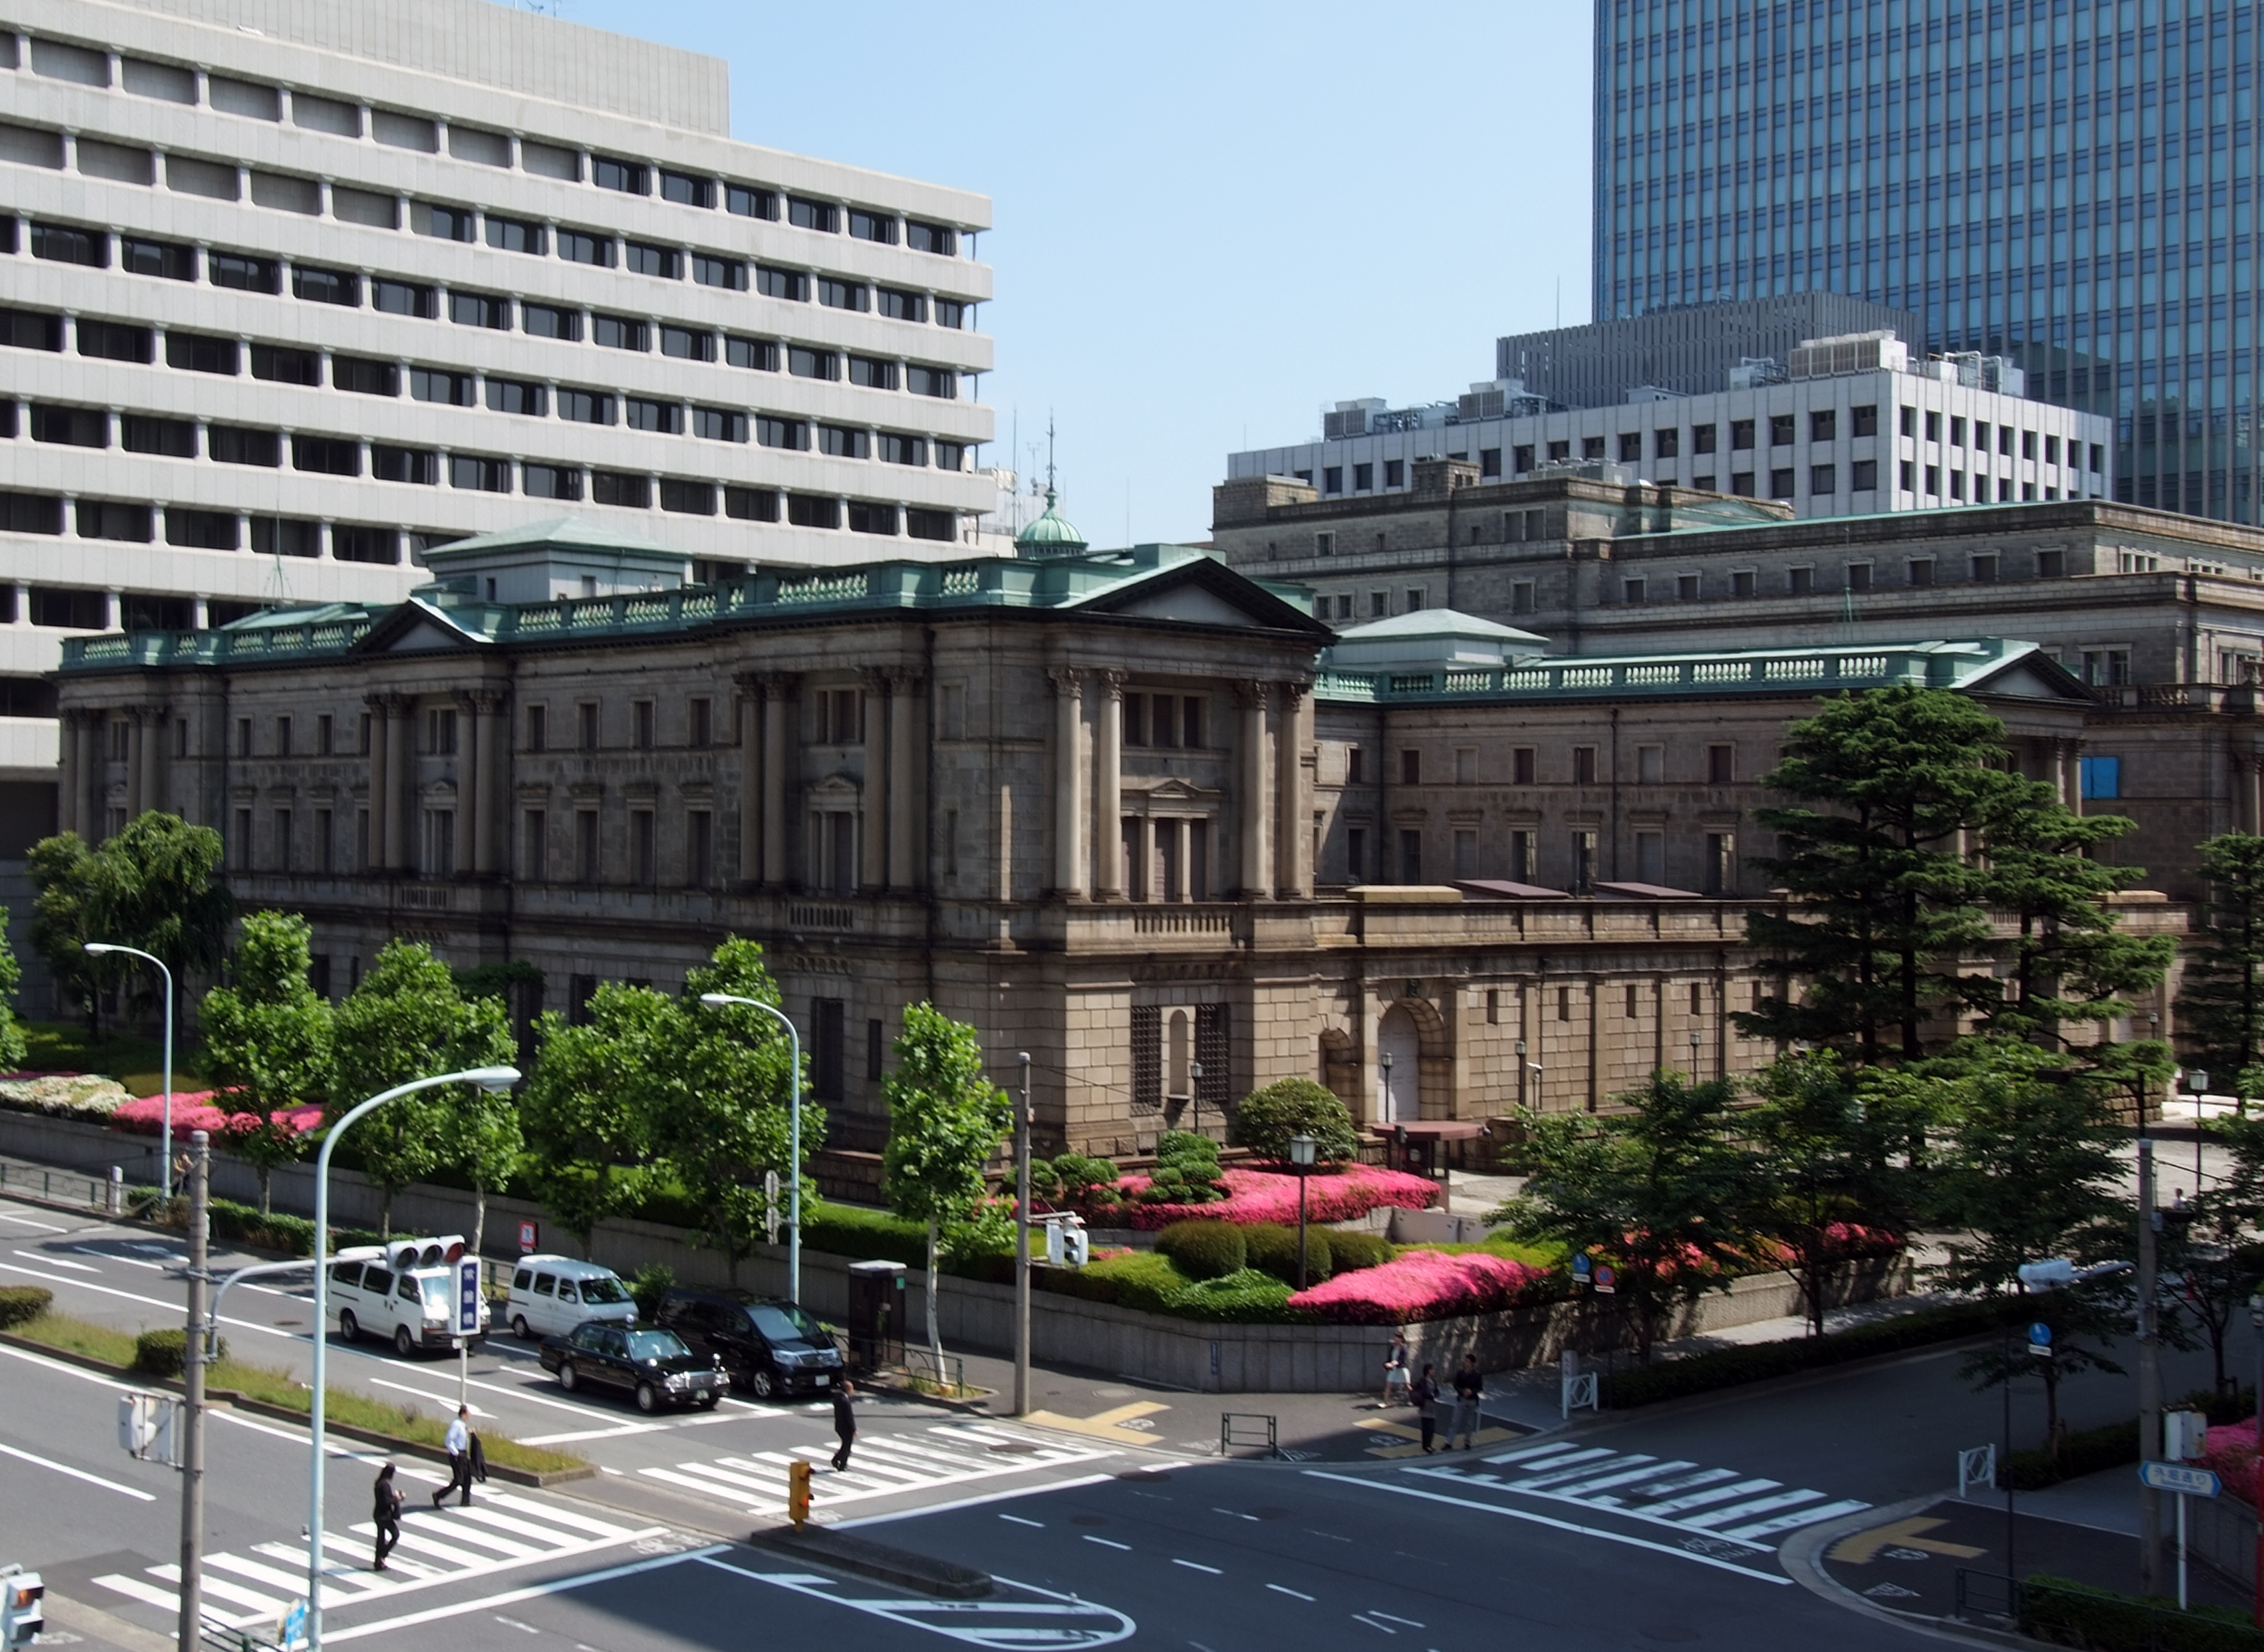
Tokyo – The Bank of Japan (BOJ) announced on Tuesday that it will raise its short‑term policy rate by a quarter of a percentage point to 1.25 percent, the highest level the nation’s central bank has set since 1995. In its statement, the BOJ cited “persistent inflationary pressures stemming from surging energy costs and a sharply weakened yen” as the primary drivers of the move, and indicated that further tightening could be on the agenda if price gains continue. The decision marks a decisive shift from the ultra‑loose stance that has defined Japanese monetary policy for more than a decade.
The rate hike comes after months of debate within the BOJ’s policy board over how best to balance price stability with the need to support a fragile domestic economy. Japan’s consumer price index has been edging above the bank’s 2 percent target, largely due to higher oil, gas and electricity prices that have risen in tandem with global energy markets. At the same time, the yen has depreciated to near‑four‑year lows against the dollar, inflating the cost of imported goods and feeding into the inflationary loop. By raising rates, the BOJ hopes to curb demand‑side pressures and reinforce the currency, while also signalling to markets that it will not tolerate a prolonged overshoot of its inflation goal.
The policy shift also reflects the delicate interplay between the BOJ’s statutory independence and the political environment in Tokyo. Although the bank is a corporate entity separate from the government, its monetary decisions fall under the broader umbrella of national economic administration. Historically, the BOJ has been granted autonomy to pursue long‑term price stability, even when short‑term political pressures have called for more stimulus or aggressive easing. In recent weeks, members of the ruling Liberal Democratic Party have voiced concerns that a weak yen is eroding household purchasing power and widening the trade deficit, while also warning that excessive tightening could stifle the still‑recovering output sector. The BOJ’s modest hike is therefore a calibrated response that attempts to respect its mandate for price stability without triggering a sharp slowdown.
Financial markets reacted swiftly to the announcement. The yen rebounded modestly against the dollar in early trade, though it remained well below its 2022 peak. Japanese government bond yields rose, reflecting higher borrowing costs for the state and corporations alike. Analysts note that the BOJ’s forward‑guidance—suggesting that further hikes are possible—has already been priced into equity valuations, but the true test will be whether the policy change can tame inflation without derailing the tentative recovery in consumer spending and business investment. The move also puts the BOJ on a more convergent path with other major central banks, such as the U.S. Federal Reserve and the Bank of England, which have been tightening in response to similar inflation dynamics.
For Taiwan and the broader East Asian region, the BOJ’s decision carries several practical implications. Japan is Taiwan’s third‑largest trading partner, and a stronger yen could make Japanese imports—particularly high‑tech components and machinery—more expensive for Taiwanese manufacturers, potentially squeezing margins in sectors that rely on cross‑border supply chains. Conversely, a firmer yen may ease competitive pressures on Taiwan’s export‑driven economy by narrowing the price advantage Japanese goods have enjoyed in global markets. Moreover, the rate hike could influence regional capital flows, as investors reassess risk‑adjusted returns in a landscape where three of the world’s largest economies are moving toward tighter monetary stances. Energy‑intensive industries in both economies may also feel the impact of higher financing costs amid ongoing volatility in global oil markets, underscoring the interconnected nature of monetary policy, trade and supply‑chain resilience in the Indo‑Pacific.
Produced by our editorial team, with AI assistance in editing.
